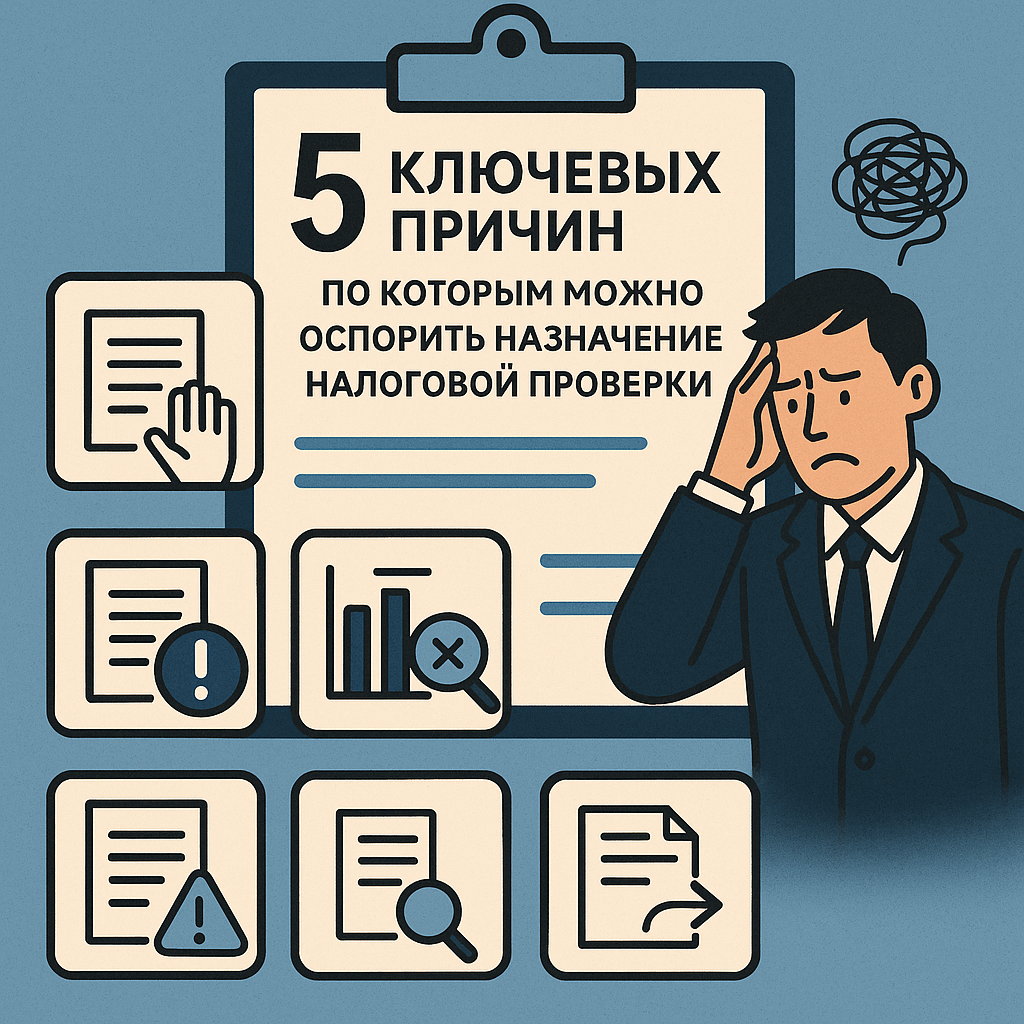
Tax audit assignments are always stressful and can result in taxes, penalties, and fines. Unfortunately, tax authority assessments aren't always justified, so it's worth defending your interests from the audit assignment procedure stage, not after receiving the results.
Let's examine the main grounds for challenging a tax audit assignment order and directive.
- Lack of Legal Grounds for Unscheduled Audit Assignment
Tax and business legislation establishes an exhaustive list of grounds for unscheduled audit assignments. If an audit is assigned without meeting these grounds (for example, without authorization from competent authorities, without applications from individuals or legal entities with supporting evidence of violations, without prosecutor's office instructions on specific facts, etc.), such assignment can be challenged.
In practice, we encounter cases where tax authorities assign audits based merely on their assumptions, which under literal interpretation of legislation is incorrect.
When such facts exist, we recommend carefully considering the feasibility of appealing tax authority acts.
- Violation of Audit Assignment Procedure
Tax audit assignment procedure requires compliance with certain requirements, such as:
- Serving notice and preliminary audit assignment decision
- Hearing taxpayer objections
- Compiling hearing minutes
- Issuing audit assignment order
- Serving tax audit directive
Violation of any of these requirements can serve as grounds for declaring the audit assignment unlawful. Violations also include the widespread practice of tax authorities ignoring taxpayer objections to preliminary decisions. Specifically, tax authorities may issue final audit assignment decisions without considering information and documents submitted during hearings.
- Methodological Issues
If the tax authority used incorrect data analysis methodology when preparing for an audit (for example, applying cash method instead of accrual method when analyzing income), this can be grounds for challenge. Such methodological errors lead to incorrect conclusions about violation existence.
4. Exceeding Preliminary Decision Scope
If the audit directive contains questions or periods not included in the preliminary audit assignment decision and not discussed during the hearing procedure, this constitutes a gross procedural violation and grounds for challenge.
It's important to remember that according to the Supreme Court's Regulatory Resolution on tax legislation application, tax audit assignment orders and directives can be independent subjects of judicial challenge within administrative proceedings, not only in conjunction with tax audit results.
A professional approach to challenging tax audit assignments requires thorough analysis of all aspects of the specific situation and legal position preparation considering current legislation and judicial practice.
Nurlan Zekenov, Partner at GK and Partners